New ATO ruling on depreciation of composite assets

The ATO has recently finalised TR 2024/1 titled Income tax: composite items — identifying the relevant depreciating asset for capital allowances (the Ruling). The Ruling sets out the relevant principles identified by the Commissioner to assist in determining whether a composite asset is just one depreciating asset or a number of separate depreciating assets for tax depreciation (Div 40 of the ITAA 1997) purposes.

The Ruling was originally issued in draft seven years ago as TR 2017/D1 and reissued as an updated draft last year as TR 2023/D2.

The relevance of composite assets

A ‘depreciating asset’ is defined in the tax law as ‘an asset with a limited effective life that can reasonably be expected to decline in value over the time it is used’ but does not include land, an item of trading stock, or intangible assets not listed in the legislation.

A composite asset is an asset that is comprised of multiple components that are capable of separate existence.

The question arises as to how to deal with composite assets for the purposes of claiming a depreciation deduction.

The law states that:

… whether or not a particular composite item is a depreciating asset or whether its components are depreciating assets is a question of fact and degree which can only be determined in light of all the circumstances of the case. [Emphasis added.]

The Ruling

The Commissioner’s view is that in order for a component — or more than one component — of a composite item to be considered to be a depreciating asset, the component must be capable of being separately identified and recognised as having commercial and economic value.

Purpose or ‘functionality’ is generally a useful guide in identifying the depreciating asset and identifies the following main principles that are to be taken into account in determining whether a composite item is a single depreciating asset, or more than one depreciating asset:
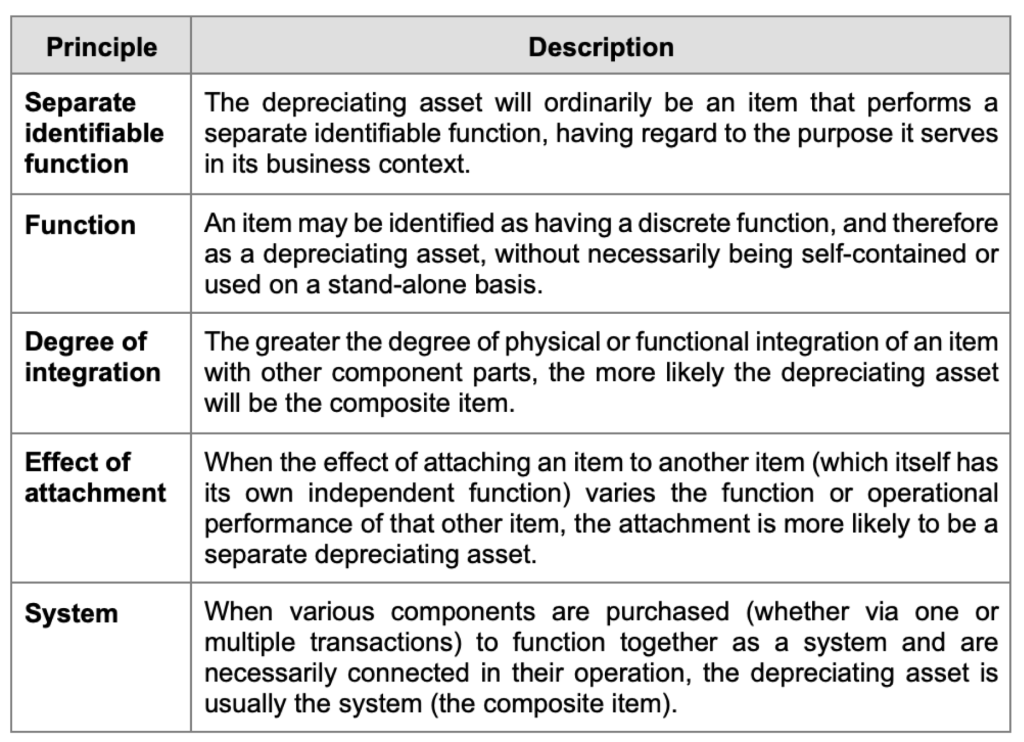
Table 1

The Ruling also considers the following issues:

  • modifications to a depreciating asset
  • jointly held tangible assets
  • intangible assets.

Practical examples

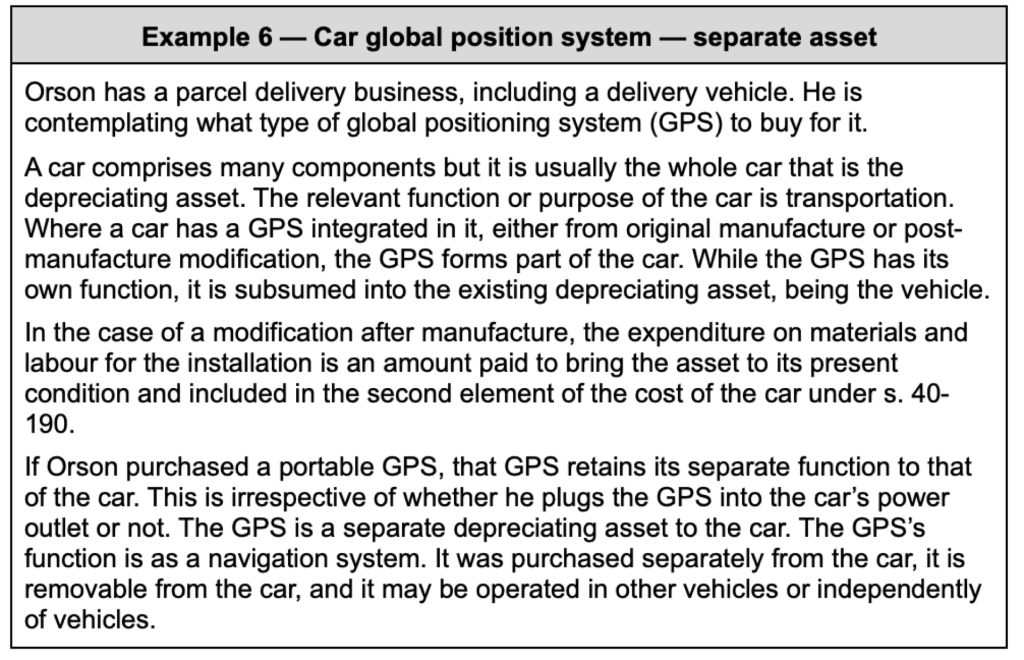
The Ruling contains 14 practical examples, including the following:
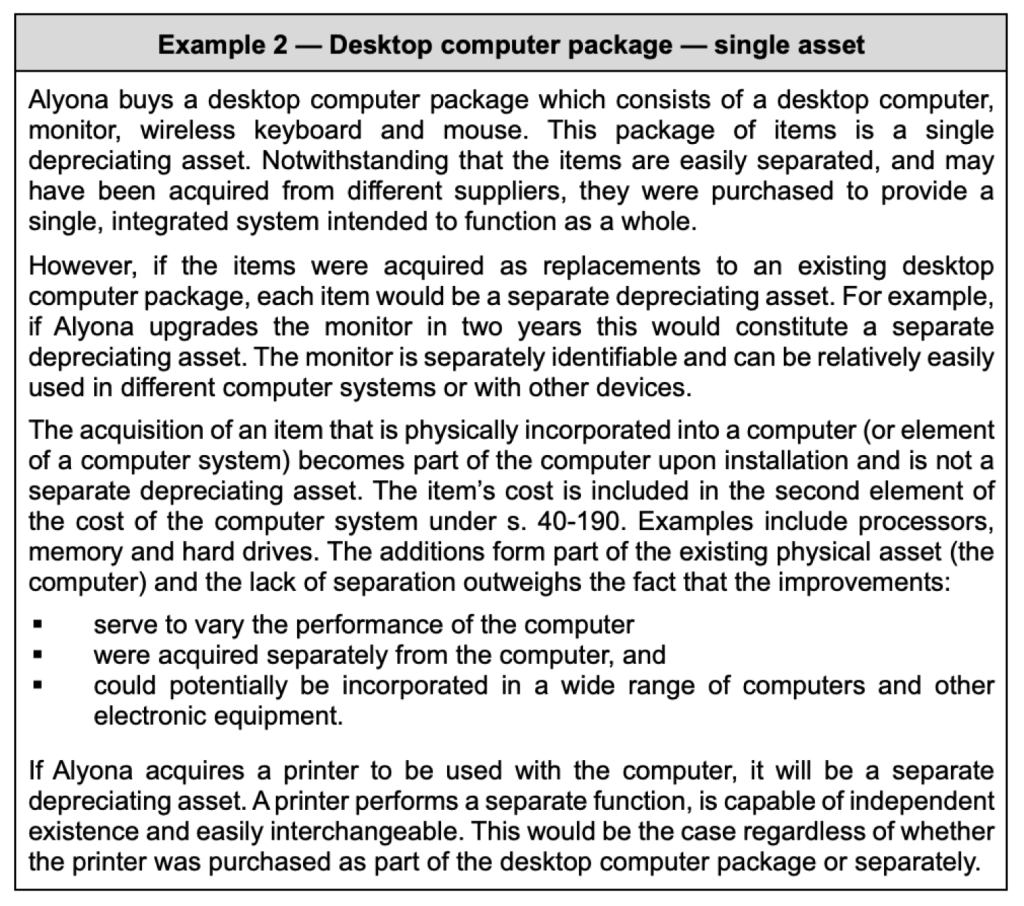
Example 2

Example 6

This information is general information only and not intended to be financial product advice, investment advice, tax advice or legal advice and should not be relied upon as such. As this information is general in nature it may omit detail that could be significant to your particular circumstances. Scenarios, examples, and comparisons are shown for illustrative purposes only. Certain industry data used may have been obtained from research, surveys or studies conducted by third parties, including industry or general publications. TaxBanter has not independently verified any such data provided by third parties or industry or general publications. No representation or warranty, express or implied, is made as to its fairness, accuracy, correctness, completeness or adequacy. We recommend that individuals seek professional advice before making any financial decisions. This information is intended to assist you as part of your own advice to your client. Use of this information is your responsibility. To the maximum extent permitted by law, TaxBanter expressly disclaims all liabilities and responsibility in respect of any expenses, losses, damages or costs incurred by any recipient as a result of the use or reliance on the information including, without limitation, any liability arising from fault or negligence or otherwise. While all care has been taken to ensure the information is correct at the time of publishing, superannuation and tax legislation can change from time to time and TaxBanter is not liable for any loss arising from reliance on this information, including reliance on information that is no longer current. Tax is only one consideration when making a financial decision. 

Stay informed with our newsletter

Join thousands of savvy Australian tax professionals and get our weekly newsletter.

Practical tax training for the year ahead

Stay ahead of Australia’s fast‑moving tax landscape with two training streams that work together to keep you sharp and up to date.
Tax Yak Cover Page 2026

Tune in to Tax Yak

Stay sharp with practical discussions from TaxBanter’s expert trainers and industry specialists.

Recent Blog Posts

Tax Yak Cover Page 2026

Episode 69: Beyond Bendel: When is a UPE not a loan?

In this episode of TaxYak, we deep dive into the burning issues resulting from the Full Federal Court's 3:0 decision in favour of the taxpayer

The Bendel Case: When is a UPE not a loan?

On 19 February 2025, the Full Federal Court (FFC) handed down its eagerly awaited decision in Commissioner of Taxation v Bendel [2025] FCAFC 15 (the

CGT Event K6: The Sleeper Tax Trap Unveiled in the ATO’s Latest Ruling

Where a shareholder has acquired shares in a private company or units in a unit trust, that were acquired prior to 20 September 1985, such
Tax Yak Cover Page 2026

Episode 68: Navigating Small Business Restructures

With a focus on eligibility and practical application, this episode dives into the complexities of restructuring options for small businesses. Whether you’re facing financial uncertainty

The Federal Budget Report is Now Available

On Tuesday 12 May, Treasurer Jim Chalmers handed down the Federal Budget. TaxBanter have prepared a detailed summary of the Government’s 2026-27 Federal Budget which is now available on the TaxBanter website.